What Happened on US 50 in Millard County on September 20, 2026?
UDOT traffic logs recorded a minor incident on Sunday, September 20, 2026, along NB US-50 E MP 141.3 in Millard County. The incident was classified as a vehicle fire with no lanes blocked. Official reports did not identify travel directions or underlying mechanical causes.
Highway emergencies in rural stretches of Utah often leave motorists stranded with immediate vehicle damage. When a crash or roadway hazard occurs, figuring out which insurance policy pays for medical treatment or property losses can quickly become confusing. Gathering the official police report promptly is always a critical early step in protecting your rights after any highway event.
How Does Utah Uninsured and Underinsured Motorist Coverage Work?
Utah law requires insurance companies to automatically include uninsured motorist (UM) and underinsured motorist (UIM) coverage on every auto policy. Under Utah Code 31A-22-305 and Utah Code 31A-22-305.3, this protection remains on your policy unless you specifically reject it in writing. Many Utah drivers carry this vital protection without realizing they have it.
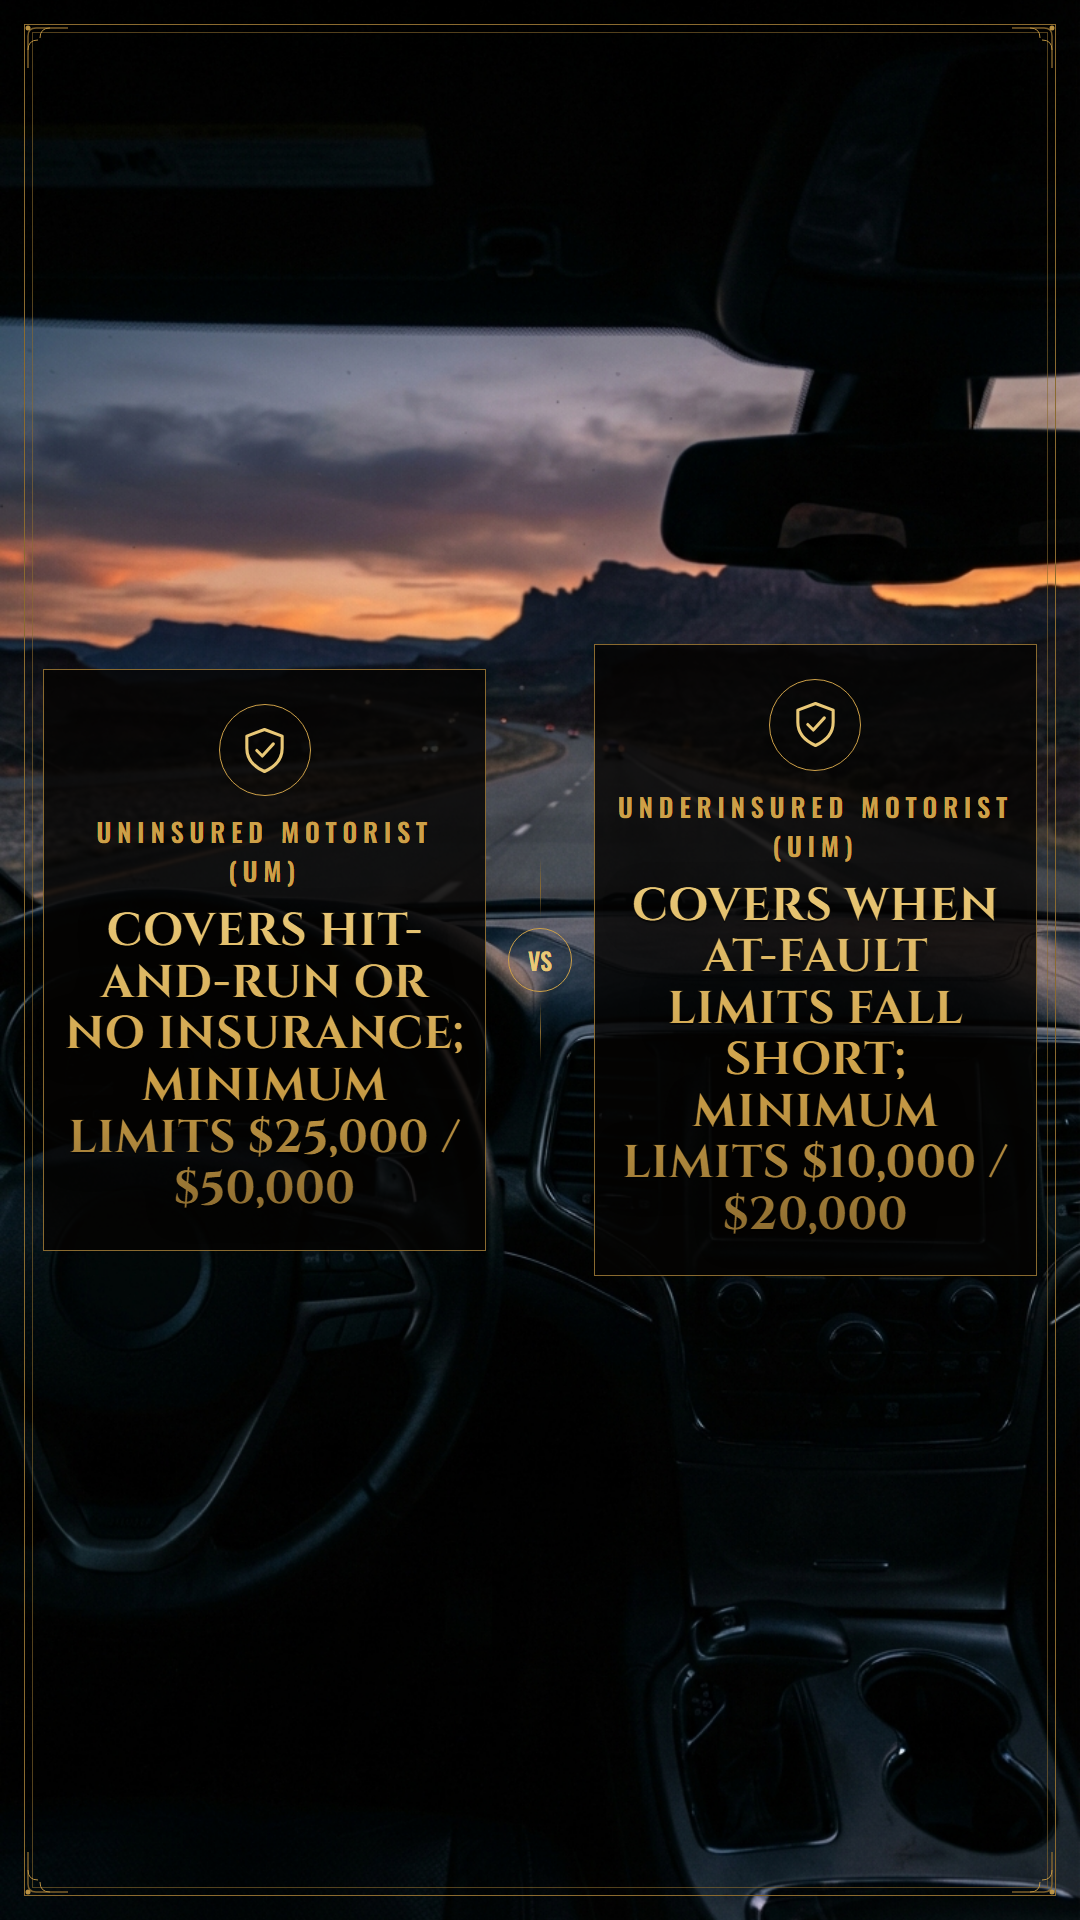
Uninsured motorist coverage applies when an at-fault driver has no liability insurance at all, or after an unidentified driver causes a hit-and-run collision. Underinsured motorist coverage steps in when an at-fault driver has active insurance, but their policy limits fall short of your actual losses. If you purchased these coverages, Utah sets minimum UM limits of $25,000 per person and $50,000 per accident, alongside minimum UIM limits of $10,000 per person and $20,000 per accident.
Filing a claim under your own policy after a car accident is still a formal insurance claim. Your own insurance carrier has a business interest in keeping payouts as low as possible, meaning an adjuster will evaluate your damages with the same scrutiny as an opposing insurer.
Why Does Reviewing Your Policy Declarations Page Matter?
Confirming whether you carry UM or UIM protection requires reading your actual policy declarations page rather than assuming what coverage exists. Many drivers assume they possess full coverage, only to discover they previously signed a waiver removing these safeguards. Reviewing the written policy documents is the only reliable way to verify your real coverage limits.
Handling an uninsured driver claim also requires securing clear documentation before critical details fade. Securing the official police report, preserving witness statements, and pulling any available roadway footage help establish the facts of the event. At The Action Firm, our team helps injured individuals review their insurance documents and understand how Utah insurance statutes apply to their specific situation.