What Happened on Northbound I-15 in Lindon on September 30, 2026?
UDOT traffic logs recorded a crash on Wednesday, September 30, 2026, along northbound I-15 at milepost 274, just south of Pleasant Grove Boulevard in Lindon. The incident was classified as minor and blocked the left shoulder without requiring a full roadway closure. UDOT reported travel direction as unknown and listed no specific data on affected lanes beyond that shoulder blockage.
When an incident occurs on a busy stretch like Utah County's interstate corridor, sorting out the aftermath starts with medical care. Many people assume fault determines who pays the doctor right away, but that is not how Utah insurance statutes operate.
How Does Utah PIP Insurance Pay Medical Bills After a Crash?
Utah operates under a no-fault auto insurance framework. If you are hurt in a collision, your initial medical bills and lost wages go directly to your own Personal Injury Protection insurer under Utah Code 31A-22-307 and Utah Code 31A-22-309. This rule applies regardless of who caused the wreck, and you file that PIP claim with your carrier before looking anywhere else.
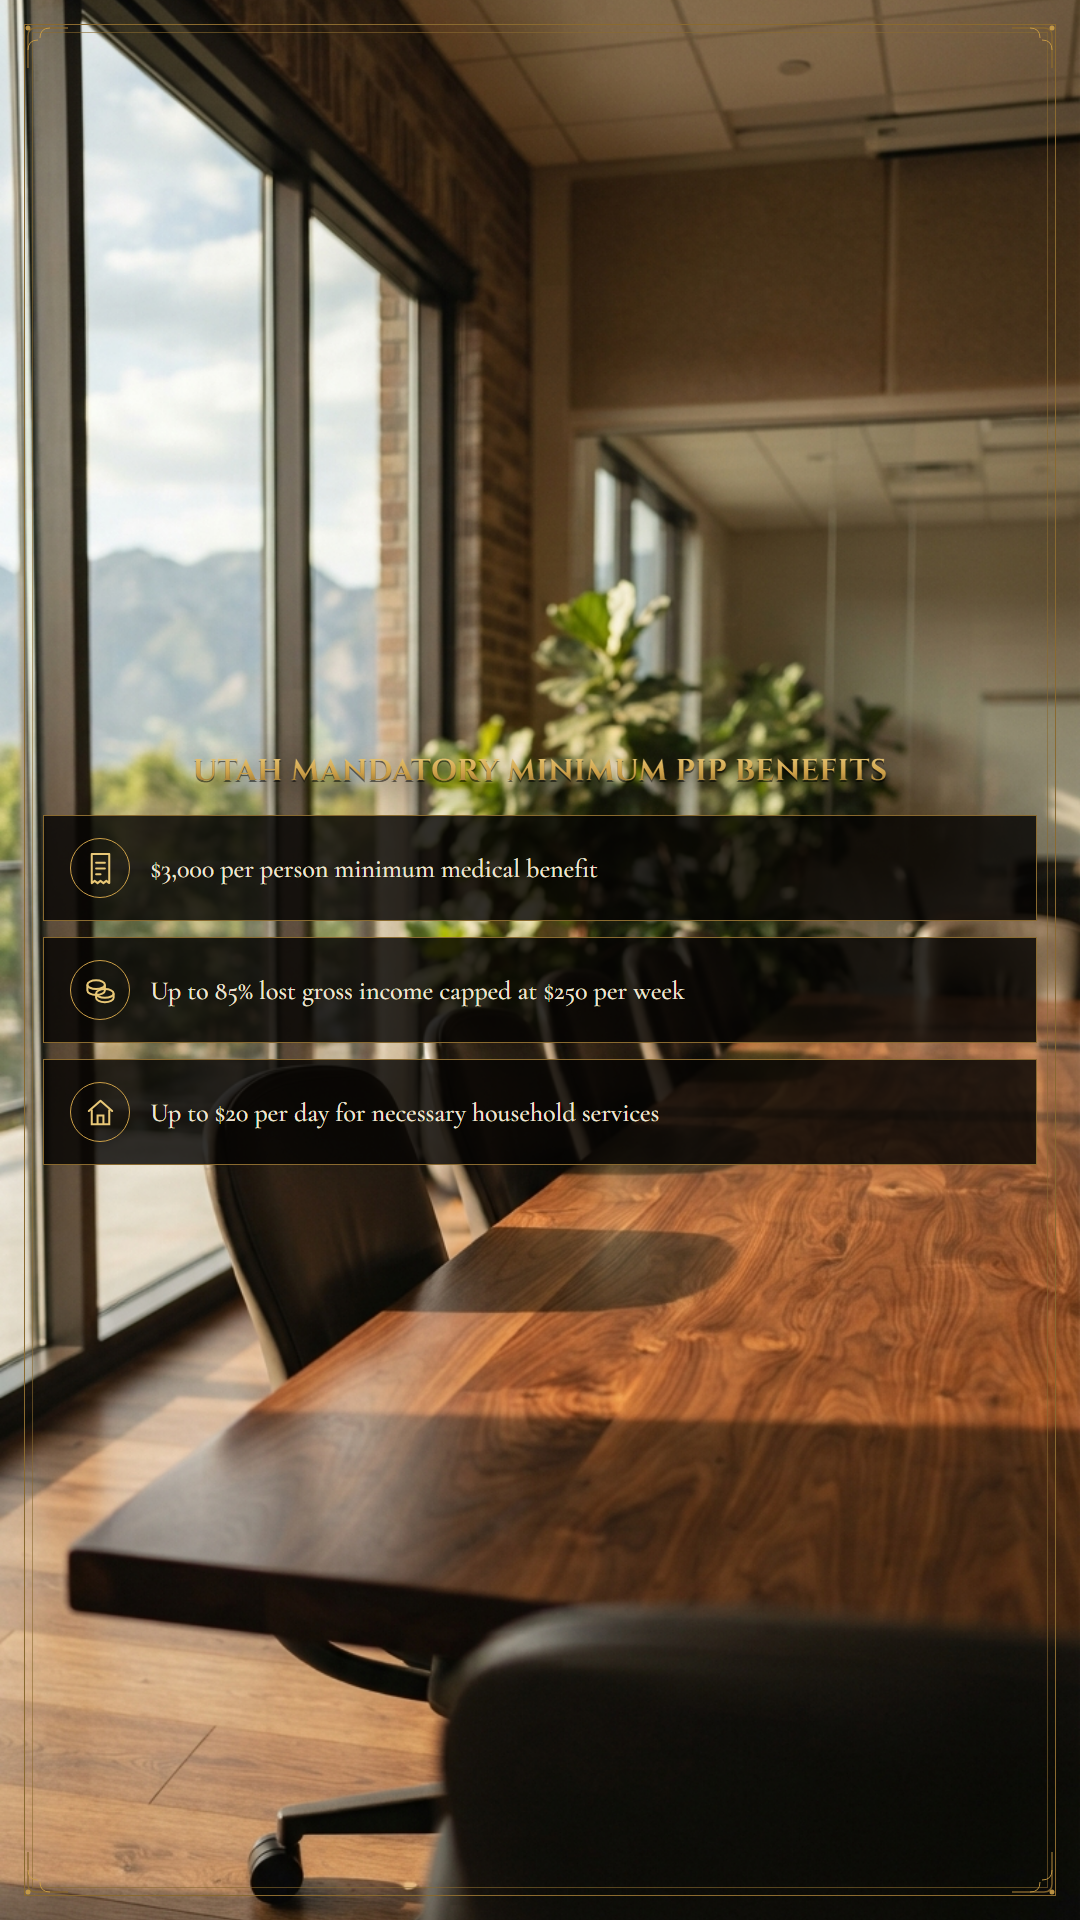
Under Utah Code 31A-22-307, the state-mandated minimum PIP medical benefit is $3,000 per person for an accident. PIP also covers up to 85% of lost gross income, capped at $250 per week under Utah Code 31A-22-309, plus up to $20 per day for necessary household services you cannot perform. Those amounts provide immediate relief, but basic emergency care or diagnostic scans can exhaust that $3,000 limit almost immediately.
If your injuries are very minor and resolve quickly within your PIP limits, you might not need a lawyer at all. At The Action Firm, we believe in telling people honestly when they can handle a claim on their own. But when treatment extends further, the financial picture changes significantly.
When Can You Make a Claim Against the At-Fault Driver?
You can pursue a separate claim against the at-fault driver once your reasonable medical expenses exceed Utah's $3,000 serious injury threshold. Crossing that statutory line allows you to seek damages that PIP never pays, including pain and suffering, medical expenses beyond your policy limit, and future medical treatment.
Insurance companies have no legal duty to inform you when your bills cross that statutory threshold. Keeping track of bills, collecting medical records, and establishing whether an injury qualifies requires methodical documentation. Whether your specific medical expenses meet the threshold is something to evaluate with an attorney rather than assuming on your own.
Handling a claim that outpaces PIP involves careful documentation of all healthcare visits and lost wages. To understand how liability and coverage operate after a wreck, reviewing resources on car accidents can help clarify the broader legal process. If you have questions about your situation, you can reach out directly through Contact The Action Firm.